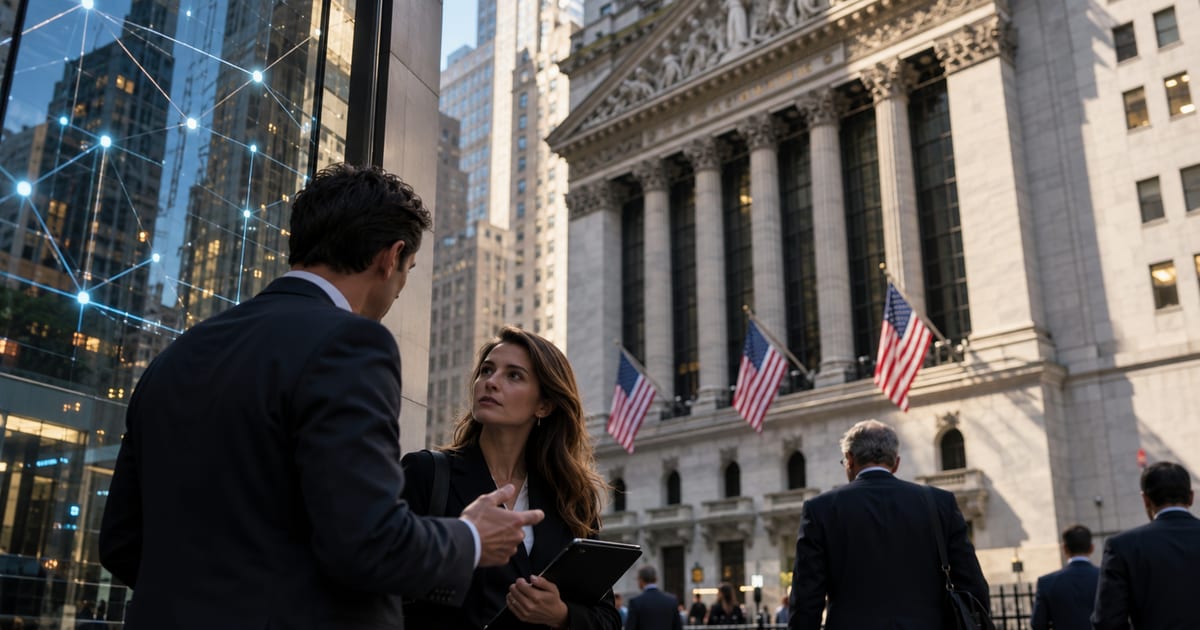
Wall Street is taking another step towards moving traditional financial markets to blockchain. DTCC, an institution serving the American securities market, has launched a tokenization service for shares, ETF funds and treasury bonds. 20 financial institutions have already secured access to it, including JPMorgan, Citi, Morgan Stanley and Bank of America. Initially, securities with a total market value of approximately USD 30 trillion may be tokenized. What does this mean for the future of investing and are we approaching the point where stocks can be traded 24 hours a day?
The importance of this information results primarily from DTCC’s position in global finance. It is one of the most important infrastructure institutions on Wall Street, responsible for handling securities transactions and settlement. In 2025, its subsidiaries processed transactions worth US$4.7 trillion (US$4.7 billion), and DTC alone holds over US$114 trillion in assets. Tokenization is no longer exclusively the domain of cryptocurrency startups and technological experiments. It goes into the infrastructure on which the daily functioning of the American capital market depends.
JPMorgan, Citi and Morgan Stanley among 20 participants. What exactly was launched?
For starters, DTS operates in two blockchain environments: Canton Network, designed for financial institutions, and a private network based on Besu technology. Over time, DTCC intends to expand the service to additional networks.
The 20 institutions that signed access agreements included: JPMorgan, Citi, Morgan Stanley, Bank of America, Barclays, BNP Paribas, UBS, Fidelity Investments, State Street and Citadel Securities. A much broader group of over 150 companies from the financial and technology sectors worked to develop the solution.
However, the mere signing of the agreement does not mean that all the above-mentioned institutions have already started tokenizing their assets. DTCC confirmed the launch of the service, but has not yet presented public data allowing to assess the scale of its use by individual participants.
This amount does not mean that assets worth USD 30 trillion have already been transferred to the blockchain. This is the value of instruments eligible for tokenization. The actual value of the tokens created may be many times lower, and DTCC has not yet published its total value.
How does DTCC tokenization of stocks and bonds work?
The mechanism is relatively simple. An institution that holds securities in DTC can have them converted into a digital form. The corresponding tokens are transferred to the participant’s registered blockchain wallet. The process also works the other way around, allowing tokens to return to traditional accounting entries.
Importantly, no new shares or additional bonds are created in this way. The token is a digital representation of the existing title to a security that still remains in a regulated DTC depository. According to the assumptions of the DTCC, the holder retains the economic rights and protection provided for a traditional financial instrument, while the official records remain under the control of the depositary.
DTCC focuses on an institutional solution that maintains the current ownership and supervision structure, but uses blockchain to improve transfers and asset management.
Will shares be able to be traded 24 hours a day?
This is one of the most interesting aspects of the new service. DTS allows you to transfer tokenized securities 24/7 between registered wallets on a supported network.
However, this does not mean that all US stocks will be automatically traded 24/7. Transferring a security, concluding a stock exchange transaction and its settlement are separate processes. The mere launch of the blockchain infrastructure does not yet ensure a 24-hour order market, liquidity and immediate settlement of each transaction.
There are also operational limitations. According to the service’s documentation, conversion requests between traditional records and tokens are accepted on business days from 2:00 a.m. to 6:00 p.m. US Eastern Time, with a target turnaround time of 15 minutes or less. 24/7 transfers apply to properly registered wallets on the same network.
It is also worth remembering that the standard settlement cycle on the US stock market is currently T+1, i.e. one business day from the conclusion of the transaction. The launch of DTS itself does not abolish this standard for traditional stock exchange trading.
This opens the way to the development of 24-hour markets for tokenized shares, although their dissemination will depend on liquidity, regulations and integration with traditional financial institutions.
Why are the largest banks investing in blockchain?
For JPMorgan or Citi, the most important benefit of tokenization does not have to be the ability to sell shares to individual investors on Sunday evening. More efficient use of securities as collateral in transactions between institutions may be of much greater importance.
Let’s imagine a bank that has a large portfolio of US treasury bonds and wants to use part of it as security for an obligation to another institution. Traditionally, such a process may require coordination between custodians, settlement systems and operational departments. Tokenization makes it possible to transfer appropriate rights to assets within the blockchain infrastructure, potentially shortening the time needed to make them available.
From the banks’ point of view, this means the possibility of increasing capital efficiency. Funds and assets that were previously less operationally accessible can be moved and used more quickly. This potentially reduces costs and reduces the need to maintain additional security measures, although actual savings will depend on the scale of implementation.
Was this text helpful?
0.00000000 BTC
The tokenization market is growing, but is still small relative to Wall Street
This is a small market compared to traditional securities. However, it is important to distinguish the actual value of existing tokens from the USD 30 trillion value of instruments eligible for tokenization by DTCC. These are different measures and should not be directly equated.
These data indicate investors’ real interest in 24/7 access to assets, but also show how much remains to be done before tokenized trading becomes a full-fledged alternative to traditional exchanges.
What will change for investors in Poland?
For now, the launch of the DTCC Tokenization Service does not mean that a Polish investor will be able to transfer his Apple or Microsoft shares to any cryptocurrency wallet. The system is intended for authorized financial institutions and their clients, and access to tokens is subject to certain requirements.
In the longer term, however, tokenization may impact the way brokerage services are used. Potential benefits include faster securities transfers, more efficient settlement, easier use of assets as collateral and the development of platforms offering trading outside standard trading hours. However, there is no guarantee that lower infrastructure costs will automatically translate into cheaper services for individual customers.
Technological and legal challenges also remain. Banks must ensure the security of digital wallets, data compliance between systems and the ability to reliably settle transactions. The dispersion of liquidity between competing blockchains may also become a problem.
Wall Street enters blockchain. Now it’s time for real scale
The launch of DTS is an important event, primarily because blockchain has been incorporated into the activities of one of the most important institutions of the American financial market. This is a clear improvement on previous tests and pilot projects, although the service itself still operates under a limited regulatory program.
DTCC announces adding additional blockchain networks in 2027. However, the success of the project will not be determined by the number of technological integrations or the names of banks on the list of participants, but by the value of actually tokenized assets, the volume of transactions and the scale of savings achieved by financial institutions.
It is also an important signal for the cryptocurrency market. The largest financial institutions are increasingly using blockchain technology without having to transfer their operations to open DeFi protocols. If this model proves successful, the future of tokenization may lie in both public blockchains and regulated institutional networks.
Wall Street has yet to move its trillion-dollar assets to the blockchain. However, it has launched infrastructure that can enable such a process on a much larger scale than before.